PCS VA Loan Housing Decisions This Fall: Buy or Rent With Rates Near 6.1 Percent?
Freddie Mac has the average 30-year mortgage rate hovering around 6.10 percent this year, a level that has cooled home buying activity broadly but has not stopped service members from using their VA loan benefit during PCS moves, since the VA loan's zero down payment structure and lack of private mortgage insurance still offer real advantages civilian buyers do not have access to at any rate. The question this fall is not whether the VA loan still makes sense, it is whether buying, versus renting, makes sense given where BAH currently sits relative to actual market conditions at a specific new duty station.
PCS VA loan housing decisions this fall sit at the intersection of two separate financial pressures that do not always point the same direction: a 2026 BAH table that is running an average 4.2 percent higher but has fallen behind actual rents by as much as 25 percent in certain high-demand markets, and mortgage rates that remain elevated compared to the sub-4 percent era many service members bought under during their last duty station.
TL;DR (Quick Summary)
2026 BAH runs an average 4.2% higher but has fallen behind rent by as much as 25% in high-demand markets
PCS VA loan housing decisions this fall depend on local market conditions, not a blanket rule
A fixed mortgage payment can protect against a rental market climbing faster than next year's BAH table
Shorter anticipated tour lengths can erase the advantage of buying due to transaction costs
Run real numbers before deciding, not assumptions from your last duty station
Why This Decision Looks Different at Different Duty Stations
In a market where local rents have outpaced BAH significantly, buying with a VA loan can make more sense than it would in a market where BAH still comfortably covers rent, because a fixed mortgage payment offers protection against a rental market continuing to climb faster than next year's BAH table can catch up to. A service member using BAH as qualifying income on a VA loan application, which lenders are generally able to count depending on the specific loan program and lender policy, may find their purchasing power in a tight rental market translates reasonably well into purchasing power for a comparable home.
The calculation looks different for a service member facing a shorter anticipated tour length, where the transaction costs of buying and then selling within two to three years, combined with a housing market that has cooled in some regions, can erase any advantage gained from a fixed housing payment. A three-year tour followed by a forced sale in a soft local market is a very different risk profile than a five-plus year assignment or a permanent change of station to a family's intended long-term home region.
What to Actually Weigh Before Deciding
Get pre-approved and know your actual VA loan entitlement and purchasing power before you start comparing it against rental listings, since an apples-to-oranges comparison between an estimated mortgage payment and an actual rental listing price leads to bad decisions. Factor in the full cost of ownership beyond the mortgage payment itself, including property taxes, insurance, and maintenance, none of which show up in a BAH-versus-rent comparison but all of which affect the real math of buying versus renting. And be honest about your anticipated time at this duty station, since the VA loan's real financial advantage compounds over years, not months.
A Simple Framework for the Decision
Run three numbers before deciding: your confirmed BAH at the new duty station, your estimated mortgage payment including taxes, insurance, and maintenance using current rates, and your realistic tour length at that installation. If the estimated all-in ownership cost sits meaningfully below what local rent would cost for a comparable home, and your tour length is long enough to absorb the transaction costs of buying and eventually selling, a VA loan purchase likely makes sense. If any of those numbers looks uncertain, particularly tour length, renting first buys time to make the decision with better information rather than locking in a choice you cannot easily undo.
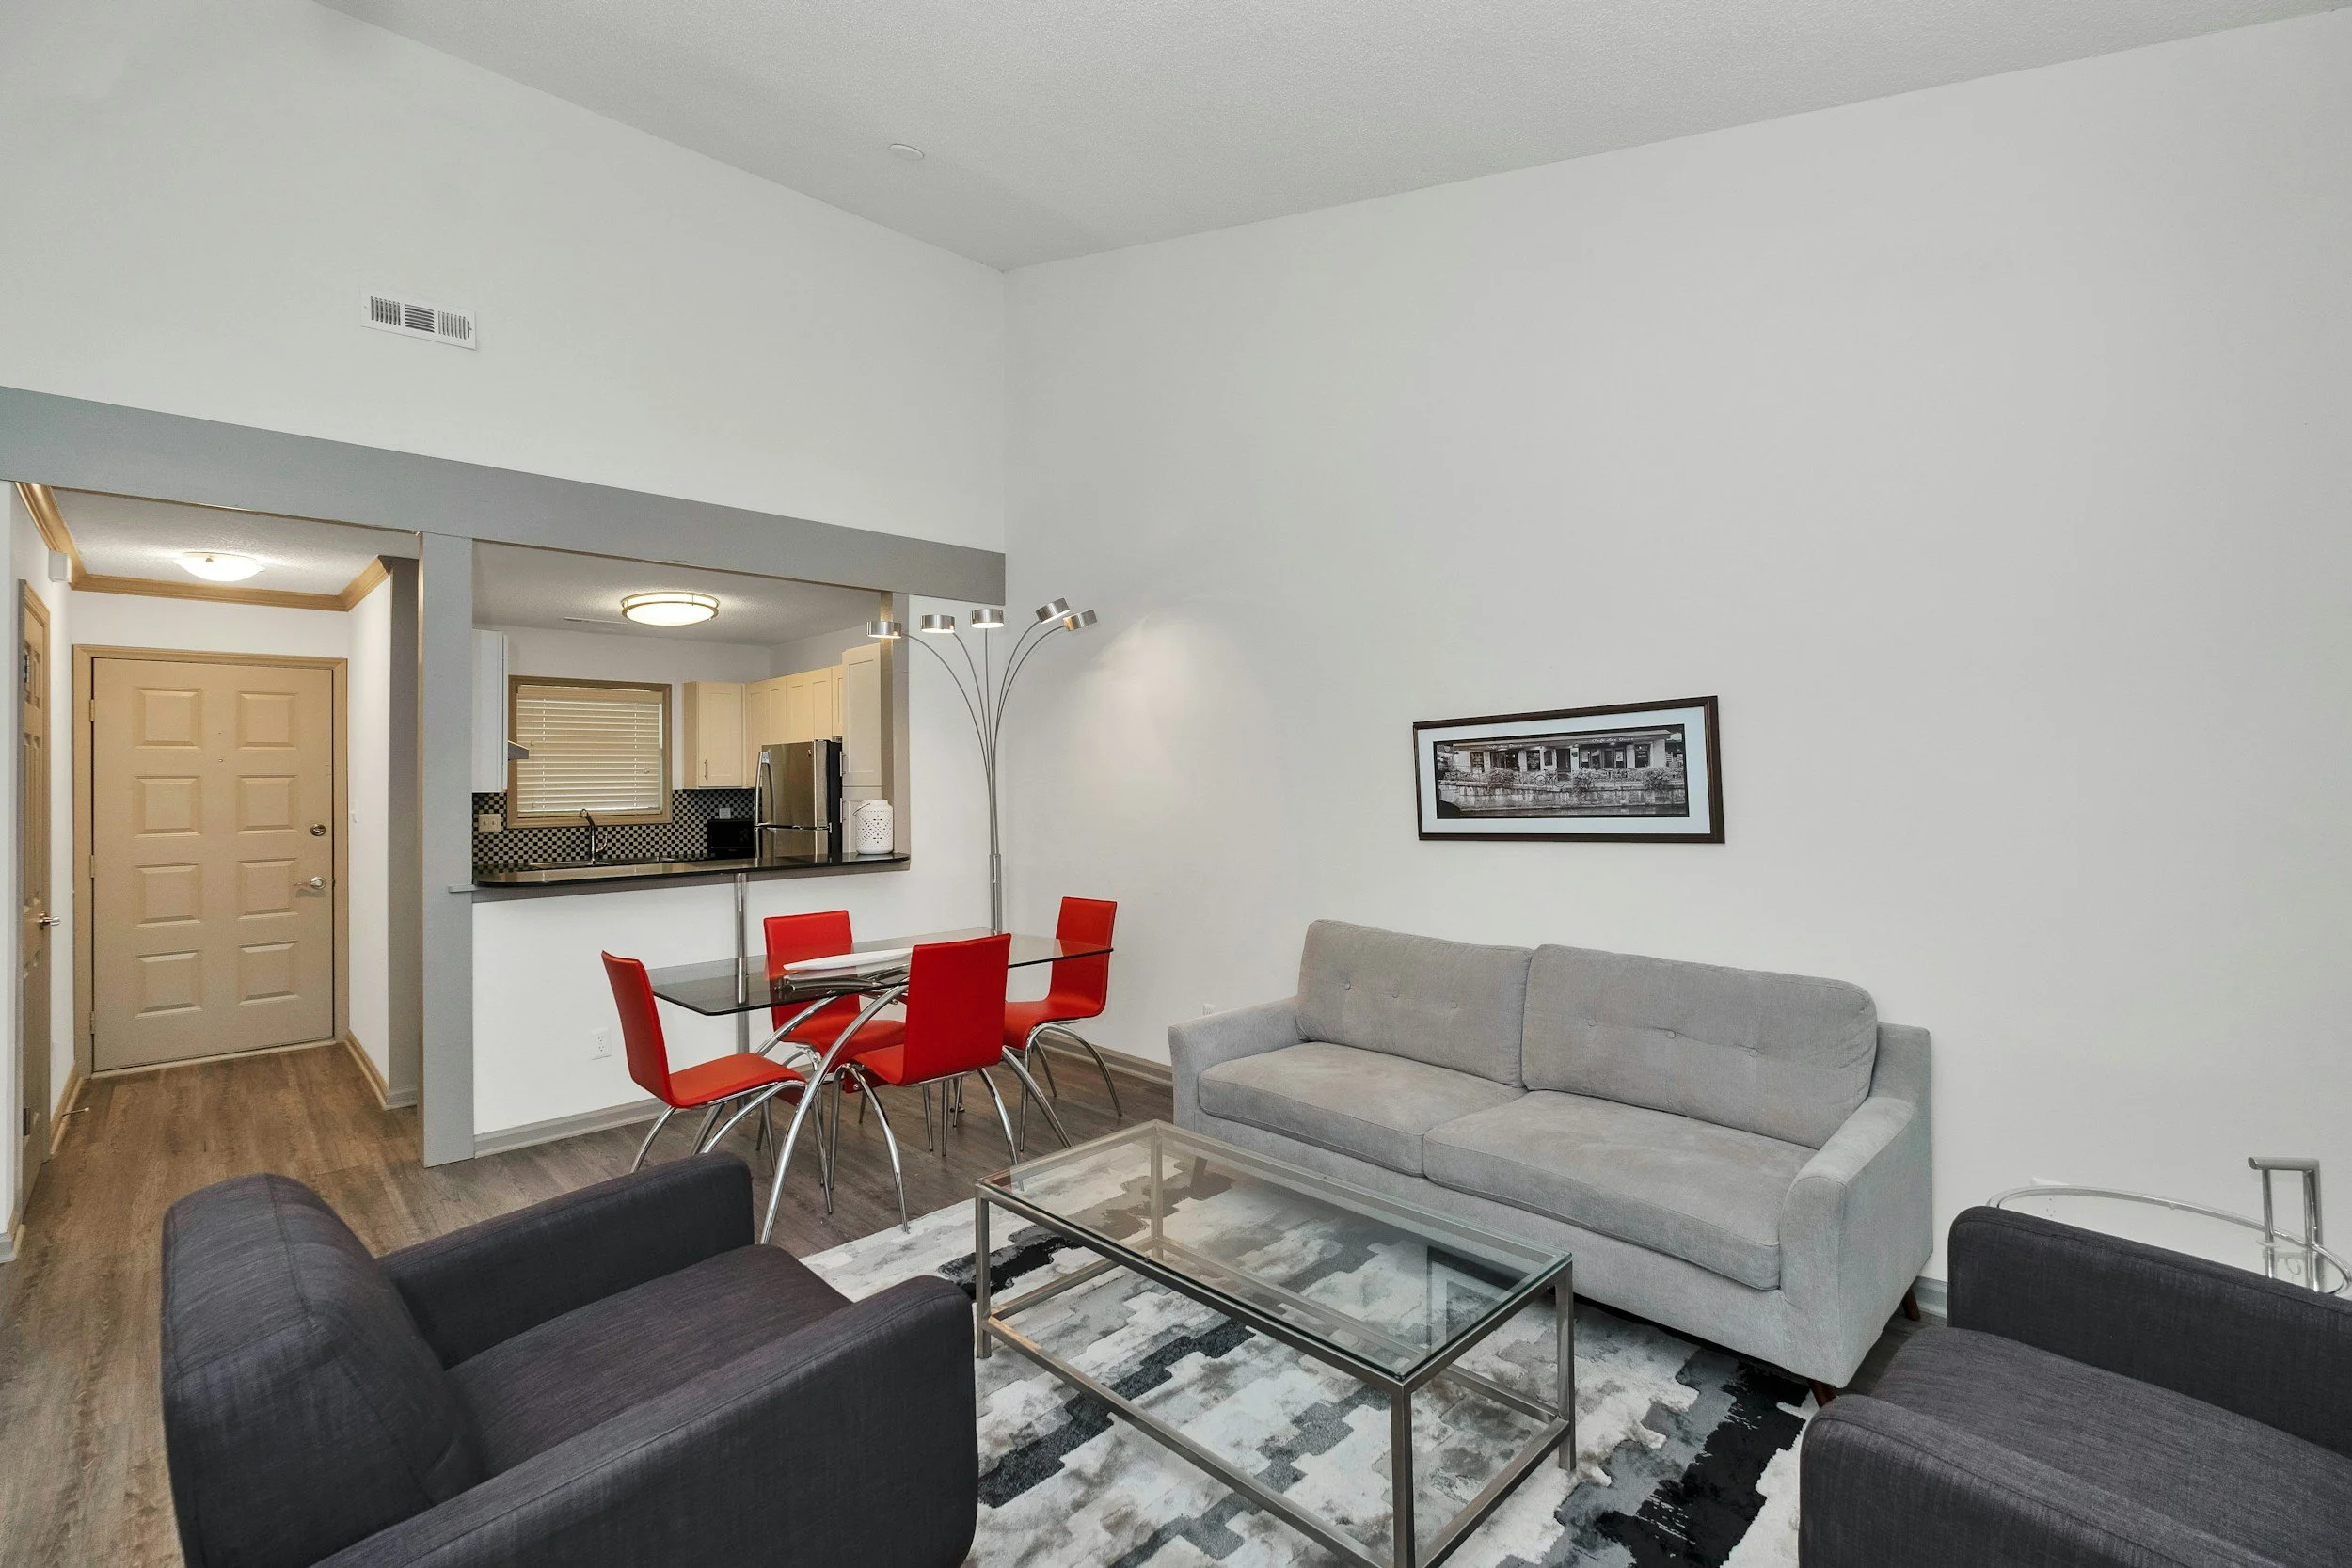
For service members who determine this is not the right duty station or timing to buy, that decision does not mean settling for a worse living situation. It means the priority shifts to finding fully furnished, move-in ready rental housing that maximizes what your actual BAH can cover.
How Lima Charlie, Inc. Helps
Lima Charlie, Inc. helps service members navigating this exact fall PCS decision find fully furnished rental housing that fits their actual, confirmed BAH, whether that housing is a bridge while you evaluate the local buying market or your plan for the full length of your tour.
Frequently Asked Questions
Is it still worth using a VA loan with rates near 6.1%?
The VA loan's zero down payment and no PMI advantages still apply regardless of rate. The buy-versus-rent decision depends more on local BAH-to-rent ratios and anticipated tour length.
Can BAH count as income on a VA loan application?
Often yes, depending on the specific loan program and lender policy.
What if I'm not sure how long I'll be at this duty station?
Renting first is usually the safer choice when tour length is uncertain, since buying and selling within two to three years can erase any financial advantage.
Final Thought
This fall's PCS buy-or-rent decision is more complicated than usual, with elevated rates and a BAH table that has fallen behind rent in some markets. Run the actual numbers for your specific station before committing either way.
Where Lima Charlie Inc. Fits In
Lima Charlie Inc. provides furnished TDY housing and off-base military lodging for service members across all six branches, with active support across 12 or more states and territories. No waitlists. No platform hunting. Just move-in ready housing built around your orders, your timeline, and your confirmed BAH.
We have supported more than 37,000 households through federally governed housing programs and bring that same standard to every military placement we manage.
Customer Service, 24/7 Support: (888) 418-4773. Real people. No automated systems. https://limacharlieinc.com/military-service-members-housing